The Four Pillars of Your Monthly Housing CommitmentWhen you transition from renting to owning a home, one of the most dangerous traps you can step into is calculating your future budget based solely

Dated: August 26 2026
Views: 50
When you transition from renting to owning a home, one of the most dangerous traps you can step into is calculating your future budget based solely on the listing price of the house. If an online mortgage calculator tells you that a loan carries a payment of $1,500 a month, that number is almost certainly incomplete.
To safely navigate through real estate, you must master the acronym PITI. These four letters represent the actual components that bundle together to create your total monthly mortgage payment: Principal, Interest, Taxes, and Insurance. [1]
Understanding how these pillars interact—and how interest heavily dominates the first third of your loan term—is the single best way to ensure your first home remains a source of wealth rather than financial stress.
The principal is the actual balance of money you borrowed from the lender to buy the home.
Interest is the cost of borrowing that money, determined by your loan’s fixed or adjustable interest rate.
This represents your local property taxes, assessed by your county or municipality to fund public infrastructure, schools, and emergency services.
This covers your mandatory homeowners insurance policy, protecting the physical asset from catastrophic damage like fires, storms, or theft.
To fully understand how PITI operates over time, you have to look at the baseline math of a standard 30-year fixed-rate mortgage.
For a baseline $400,000 loan balance at a 6.5% interest rate, your static, combined principal and interest (P&I) payment sits firmly at $2,528.27 each month, equating to $30,339.24 annually. Property taxes and homeowners insurance are added on top of this base amount.
The visual timeline below demonstrates the stark contrast between interest charges and principal accumulation across the full 30-year horizon, highlighting the critical first third (Years 1–10) milestone.
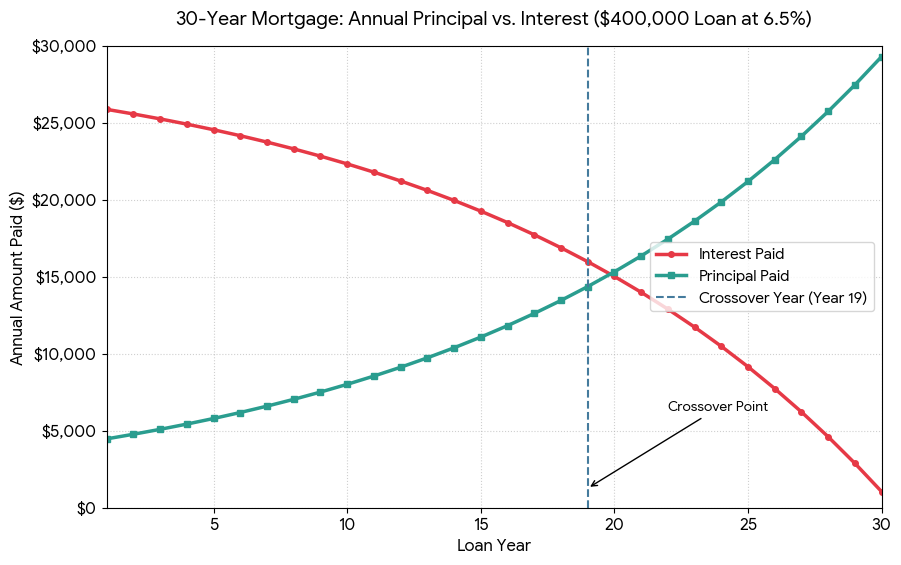
During the first 10 years of your loan, your payments are overwhelmingly absorbed by interest. Because the 6.5% interest rate is calculated against your remaining high loan balance each month, your early payments do very little to reduce the principal.
Timeline | Total Annual P&I Paid | 🛑 Amount Absorbed by Interest | 🏠 Amount Added to Your Equity |
Year 1 | $30,339.24 | $25,868.36 (85%) | $4,470.90 (15%) |
Year 2 | $30,339.24 | $25,568.94 (84%) | $4,770.33 (16%) |
Year 3 | $30,339.24 | $25,249.46 (83%) | $5,089.80 (17%) |
Year 4 | $30,339.24 | $24,908.59 (82%) | $5,430.68 (18%) |
Year 5 | $30,339.24 | $24,544.88 (81%) | $5,794.38 (19%) |
Year 6 | $30,339.24 | $24,156.82 (80%) | $6,182.44 (20%) |
Year 7 | $30,339.24 | $23,742.78 (78%) | $6,596.49 (22%) |
Year 8 | $30,339.24 | $23,301.00 (77%) | $7,038.27 (23%) |
Year 9 | $30,339.24 | $22,829.63 (75%) | $7,509.64 (25%) |
Year 10 | $30,339.24 | $22,326.70 (74%) | $8,012.57 (26%) |
PITI Component | Where Does the Money Go? | Can It Change Over Time? | Strategy for First-Time Buyers |
Principal | Directly reduces your loan balance | Fixed (on fixed-rate loans) | Making extra principal payments early cuts years off the loan term. |
Interest | The bank's profit fee for the loan | Fixed (on fixed-rate loans) | A higher credit score lowers this rate, saving thousands. |
Taxes | Local county/city government | Yes (Changes with municipal assessments) | File for a homestead exemption immediately to protect your rate. |
Insurance | Your chosen insurance provider | Yes (Changes with provider rate adjustments) | Shop your homeowners insurance policy annually to keep costs low. |
As a first-time homebuyer, always ask your lender for a comprehensive breakdown of the estimated PITI for a property before you submit an offer. Knowing the true, unvarnished monthly cost—and understanding how the amortization curve works—is your ultimate tool for long-term financial clarity.
Join our educational community on Facebook: Omaha First-Time Homebuyer Navigation It’s a dedicated knowledge hub where you can connect with local home buying experts, lenders, and inspectors to get reliable answers and market insights in a zero-pressure learning environment.
Crystal Kosnjek | Real Estate AgentI help you navigate. The decisions are always yours.I'm a real estate agent with a simple goal: helping people find more than a house. I help them find home. To me, ....
The Four Pillars of Your Monthly Housing CommitmentWhen you transition from renting to owning a home, one of the most dangerous traps you can step into is calculating your future budget based solely
 This data is from various Participants of the Great Plains REALTORS® Multiple Listing Service Inc Internet Data Exchange; is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing; the listing broker is listed on each listing; the information is deemed reliable but not guaranteed, and is copyrighted ©2026 Great Plains REALTORS® Multiple Listing Service, Inc. Information is
deemed reliable but is not guaranteed. Updated on September 14, 2026 5:04 PM UTC
Show More...
